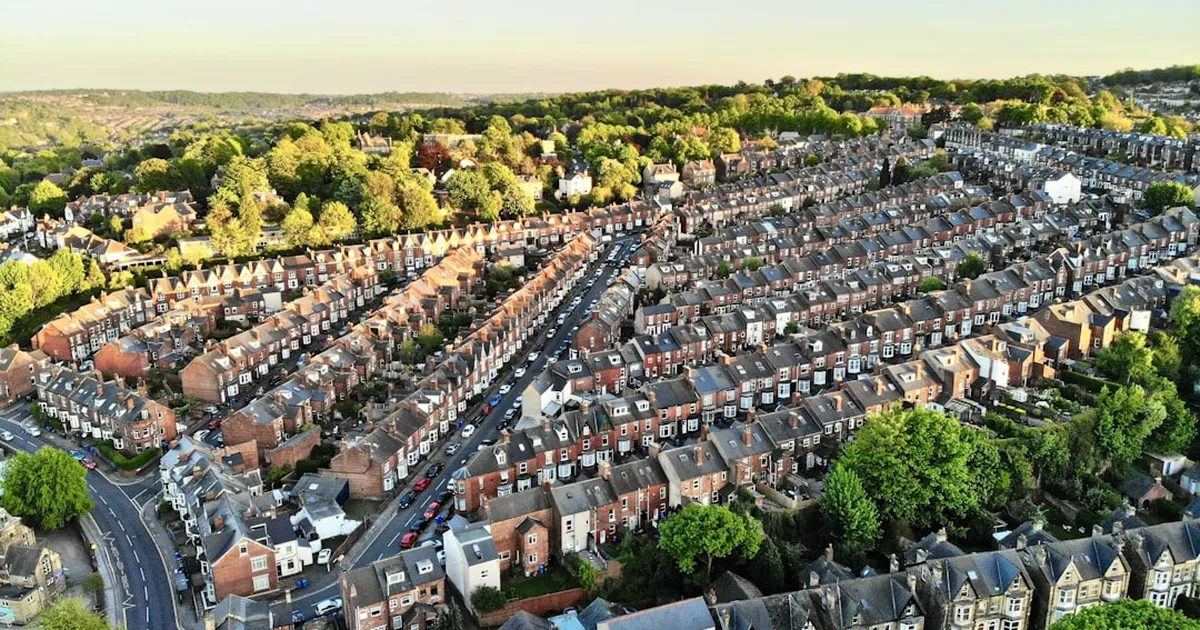
 Photo by BEN ELLIOTT on Unsplash
UK house prices drop for first time since 2023, HMRC pension tax refunds land, and new Chancellor Healey sets his Budget agenda. Here's what it means for you.
Photo by BEN ELLIOTT on Unsplash
It has been a busy 24 hours in UK personal finance. House prices have recorded their first annual fall in nearly three years, a million people — mostly women — are being contacted about pension tax refunds they are owed, and new Chancellor John Healey has laid out his stall ahead of an October Budget that looks set to shape household finances for years to come. Here is what you need to know.
The average UK home now costs £298,468, down 0.4% year on year in August, according to data published by Lloyds. That is the first annual price fall since November 2023 and came in well below the 0.2% rise that economists had been forecasting. London and the south-east are leading the decline, where stretched affordability has long been the sharpest pain point for buyers.
The culprits are familiar: higher mortgage rates, geopolitical uncertainty and the simple fact that wages have not kept pace with the property prices of recent years. For buyers who have been waiting on the sidelines, a falling market can feel like an opportunity — but it is worth remembering that mortgage costs remain elevated, meaning your monthly repayments could still be significantly higher than they were two or three years ago even if the purchase price is lower.
Watch out: Falling house prices do not automatically mean now is the right time to buy. If you are stretching to afford repayments at current rates, a modest price dip may not offset the cost of a higher-rate mortgage. Use a whole-of-market adviser to stress-test your budget before committing.
For existing homeowners, a 0.4% annual dip is unlikely to cause panic — especially if you have owned your property for several years and have built up meaningful equity. However, if you bought recently with a small deposit or are coming off a fixed-rate deal shortly, it is sensible to check your loan-to-value ratio before remortgaging, as falling prices can push you into a higher LTV bracket and therefore a less competitive rate. See our remortgage guide for more on how this works in practice.
Around one million people — the majority of them women — are owed pension tax relief that HMRC failed to apply correctly, and letters are now being sent out to notify those affected. The BBC reports that refunds in the region of £70 are expected for many recipients, though amounts will vary depending on individual circumstances and how long the underpayment has been accumulating.
The issue relates to a long-standing quirk in how tax relief is calculated on pension contributions for lower earners, particularly those whose employers use a "net pay" arrangement rather than "relief at source". Workers earning below the personal allowance threshold have historically missed out on the 20% top-up they are entitled to. This is money that was always yours — HMRC is simply returning it.
Good news: If you receive a letter from HMRC about a pension tax refund, it is legitimate. You do not need to click any links or call any numbers — HMRC will process the refund automatically in most cases. If you are unsure whether you might be affected, check with your employer about which pension scheme arrangement is in place. See our guide to how pensions work for a fuller explanation of tax relief.
This story also serves as a timely reminder to review your overall pension position. Many people — particularly those who have changed jobs multiple times — have pension pots scattered across different providers, some of which may have been subject to the same tax relief issue. A qualified financial adviser can help you track down old pensions and ensure you are getting the contributions and reliefs you are entitled to going forward. Our pension consolidation guide is a good place to start.
John Healey — who replaced Rachel Reeves as Chancellor in July after Andy Burnham became Prime Minister — gave his first major economic speech on Sunday, saying that boosting growth will be his defining mission. He stressed the need for Labour to "be honest" about public spending pressures while pledging to stick to the government's fiscal rules. Importantly, he declined to confirm whether taxes would rise in the 28 October Budget, fuelling speculation in Westminster and among business leaders.
Healey's tone was notably more optimistic than recent economic rhetoric, calling for "confidence about Britain" even as the UK faces what he acknowledged were "historic high" borrowing costs. Prime Minister Burnham is due to meet leading company bosses next week in a bid to reassure the private sector ahead of the Budget — a sign that the new administration is acutely aware that business confidence is fragile. Analysts note that any attempt to boost growth through spending could collide directly with the fiscal rules Healey says he will not abandon.
Budget watch: The 28 October Budget is shaping up to be a significant one for household finances. Corporate tax changes, income tax thresholds, pension contribution limits and capital gains tax rates are all in play. Now is an excellent time to review your financial plan with an adviser before any changes are announced — some reliefs may be easier to lock in before Budget day than after.
For everyday consumers, the key question is what the Budget means for take-home pay, mortgage affordability and savings. If borrowing costs remain at elevated levels — as Healey's "historic high" comment implies — there is little near-term relief expected on mortgage rates from the fiscal side. The Bank of England's decisions on the base rate remain the main lever. In the meantime, making sure your savings are working as hard as possible in a high-rate environment is one of the few silver linings on offer. Our ISA guide covers how to make the most of your tax-free allowance before the tax year ends.
A separate but deeply connected property story: England's housing courts are described as being at "breaking point", with up to 29 cases dealt with in a single day at some courts. The pressure has been driven by a wave of landlords selling their properties — partly in response to higher mortgage costs and tighter regulation — and tenants who have nowhere to go attempting to delay evictions. No-fault evictions under Section 21 were recently banned, but tenants caught in the system before the ban took effect are still working through the courts.
For renters, this is a stark illustration of just how difficult the private rental market has become. With fewer available properties and rising rents, those facing eviction are finding local councils overwhelmed and emergency housing scarce. If you are a renter who has received any form of eviction notice, seek legal advice as early as possible — housing charities such as Shelter offer free guidance and can help you understand your rights.
For landlords: If you are a buy-to-let owner considering selling up, it is worth taking professional financial advice before you act. Selling a rental property has capital gains tax implications, and the timing of a sale relative to the October Budget could be significant if CGT rates change. See our buy-to-let mortgage guide for more context on the current landscape.
This week's news paints a picture of a UK economy under pressure from multiple directions at once — cooling house prices, strained public services, high borrowing costs and a new government still finding its footing. Here is what we recommend you focus on right now:
A qualified, FCA-regulated financial adviser can help you navigate all of these issues with a clear head and a plan tailored to your circumstances. Nesto matches you with the right adviser for free — whether your priority is your mortgage, your pension or your savings strategy ahead of the Budget.
Get matched with an FCA-regulated adviser in under 2 minutes. Free, no obligation.
Find my adviser — it's free →Trusted by thousands of UK consumers • 5-star rated • 100% free